If you've been following the news over the past few weeks, you may have seen the headlines about Bathla Group, one of Sydney's largest home builders, collapsing into administration owing lenders more than $3 billion. Here's our take on what it means, both for the tens of thousands of families waiting on new homes, and for the private credit funds that lent Bathla the money.
Bathla Group, a family-owned developer that has built affordable homes across Western Sydney (and more recently regional NSW, South Australia and Victoria) for almost three decades, entered voluntary administration in late August. Restructuring firm Teneo was appointed to work out whether the business can be saved, sold or wound up. Bathla's founders pointed to a “perfect storm”: softening sales, falling prices, rising construction costs and changes to property taxes in this year's federal Budget. Builder collapses aren't new in Australia, but the scale here is. Bathla had tens of thousands of homes in its pipeline. Administrators have since stood down most head-office staff and secured short-term funding from a handful of lenders to keep some sites moving while longer-term options are worked through. The situation is still developing, so some details may shift by the time you read this.
Here's the part that's caught investors' attention: most of that $3 billion wasn't owed to the big banks. It was owed to private credit, funds that lend directly to businesses and developers outside the traditional banking system, in return for an interest rate typically higher than a term deposit or bank bond. Private credit has grown rapidly in Australia as investors have chased that extra yield. Reports suggest around 40 separate private credit funds had money lent to Bathla, with exposures ranging from a few million dollars to well over a hundred million. In the aftermath, several of those funds have paused investor withdrawals while they assess the damage; a reminder that unlisted, illiquid investments don't always let you access your money on demand.
Australia's corporate regulator, ASIC, has called Bathla the first real test for the private credit sector, which now manages roughly $200 billion for Australian investors. ASIC had already been pushing fund managers to lift standards around valuations, disclosure and governance (including a set of ten principles for “private credit done well” released late last year), well before this collapse. Bathla has only sharpened that focus, and we'd expect closer regulatory scrutiny of the sector from here.
None of the funds we currently use on behalf of clients carry any exposure to Bathla. That's not luck, it reflects the ongoing work we do assessing private credit managers: their loan underwriting standards; the sometimes complex structures within these managers, their funds, and the companies they lend to (see below); borrower or sector concentration in their loan books; how they value assets to lend against and the ongoing value they assign to each loan they issue; our assessment of the risk of their lending activities and the required return to compensate for that risk; and how transparent they are with investors regarding regular communications and disclosures.
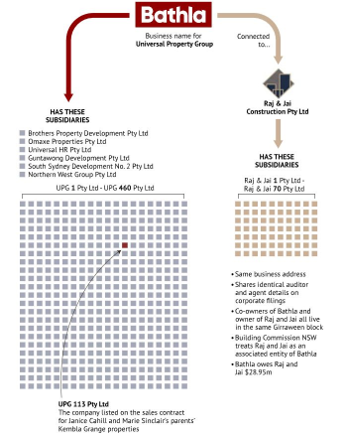
The graphic below shows the complicated structures sitting below the Bathla group. Complicated structures create opacity and make it more difficult to assess risk.
Private credit can still be a sensible part of a diversified portfolio, but this collapse is a timely reminder of how much manager selection (due diligence & monitoring) matters.
Individual companies fail in every property cycle (and economic cycle), that isn't new, and it isn't a reason to avoid property or credit exposure altogether. What matters is not being overexposed to any single company, sector or manager, and backing managers who take governance and transparency seriously. A well-diversified, long-term portfolio is built to absorb events like this without derailing your plans. If you'd like to talk through your own exposure to private credit, please speak to your adviser.
General Advice Warning - Any advice included in this article has been prepared without taking into account your objectives, financial situation or needs. Before acting on the advice, you should consider whether it's appropriate to you, in light of your objectives, financial situation or needs.
The Investment & Research team at PSK are always monitoring market conditions and data points to ensure portfolios align with our overall long-term objectives. If you’d like to discuss any of the points raised, please contact your Adviser or call us on (02) 8365 8300.


